Explore:
Defense Industry
Defense Industry
Defense Industry
 The traditional defense industry provides products and services to the DoD. Products include aircraft, ships, vehicles, weaponry, and electronic systems, while services can include logistics, technical, training, communications, and engineering support in cooperation with the government.
The DoW seeks to tap tech startups, small businesses, and other non-traditional defense contractors to rapidly exploit leading technologies to shape future defense solutions.
Defense Sectors
Air
Manned Combat Aircraft
Lockheed Martin | Northrop Grumman | Boeing | General Dynamics | Textron/Bell
Rotary Wing Aircraft
Sikorsky (Lockheed Martin) | Bell Textron | Boeing | Leonardo DRS
Large Unmanned Aerial Systems (UAS)
General Atomics ASI | Northrop Grumman | Boeing | L3Harris | Sierra Nevada Corporation
Collaborative Combat Aircraft
Anduril Industries | General Atomics | Lockheed Martin | Boeing | Northrop Grumman | Shield AI | RTX (Collins Aerospace) | Skydio
Tactical & Attritable UAS - Group 3
Kratos | AeroVironment | Textron Systems | General Dynamics | Joby Aviation | Reliable Robotics | Skyryse | Atropos | SpekreWorks
Small UAS, Micro UAS & Loitering Munitions - Group 1 and 2
Skydio | AeroVironment | Anduril | Swarm Technologies | Brinc Drones | DarkHive | PDW | GridAero | Neros | Swan | Vector
Hypersonic and High-Speed Aircraft
Hermeus | Lockheed Martin Skunk Works | Northrop Grumman | Boom Supersonic | Stratolaunch | Venue Aerospace | Long Wall
Propulsion & Engines
GE Aerospace | Pratt & Whitney (RTX) | Parker Hannifin | Ursa Major | L3Harris / Aerojet Rocketdyne | X-Bow Systems | Anduril | Northrop Grumman Innovation Systems | Galodyne
Missiles, Strike Weapons and Air-Launched Munitions
RTX | Northrop Grumman | Lockheed Martin | Boeing | L3Harris / Aerojet Rocketdyne | Castelion | Perseus Defense | Firehawk Aerospace
Autonomy Software and AI
Shield AI | Skydio | Reliable Robotics | Palantir | Anduril | Applied Intuition | Scale AI
Avionics, Sensors, EW, and Mission Systems
RTX | L3Harris | Northrop Grumman | Elbit Systems of America | Leonardo DRS | Parker Hannifin
Maritime
Shipbuilding and Naval Construction
HII | General Dynamics NASSCO | General Dynamics Electric Boat | Fincantieri | Austal USA | VT Halter Marine | Metal Shark | BMT
Unmanned Surface Vessels (USVs)
Anduril | Leidos | Saronic | L3Harris | Textron | Saildrone | Sea Machines | Martac | ThayerMahan | Ocean Aero | Seasats | HavocAI | X-Ocean | Ocean Infinity | Saab | Frost Unmanned | ST Engineering | Maritime Robotics | VATN | Odin Dynamics
Maritime Autonomy Systems and Software
Sea Machines | Nauticus Robotics | Ghost Robotics | Avikus | Dynautics | Wartsila | Anschutz | Atlas Elektronik | Acua Ocean | RoboSys | Cellula Robotics | Navtor | Greenroom Robotics | Magnet Systems | OPT | RoBoat
Submarines
HII | General Dynamics Electric Boat
Unmanned Underwater Vehicles (UUVs)
L3Harris | Boeing | Leidos | General Dynamics | Anduril | HII | Kongsberg | Lockheed Martin | Northrop Grumman | Oceaneering | QinetiQ | Textron | Kraken Robotics | Tethys Robotics | Hydrotwin | ECA Group | Exail | RTSys | Boxfish Robotics | Blueye
Combat and Weapon Systems
RTX / Raytheon | Lockheed Martin | Northrop Grumman | BAE Systems | Leonardo DRS | Elbit Systems of America | Kongsberg
Sonar, Undersea Warfare and C2
Thales Defense and Security | Ultra Maritime | Serco | SAIC | Kraken Robotics | Teledyne Technologies | Atlas Elektronik
Mine Warfare and Undersea Systems
Northrop Grumman | General Dynamics Mission Systems | Teledyne Technologies | ECA Group | Exail | Kongsberg
Propulsion, Engineering and Subsystems
GE Vernova | Rolls-Royce North America | BWX Technologies | DRS Technologies | Wartsila | ABB Marine
Ocean Data, Intelligence and Analytics
Fugro | Teledyne Technologies | Leidos | Seasats | Sofar Ocean | Bedrock Ocean Exploration | North.io | Forcys | Terradepth | Mythos AI | OpenOcean | Dark Ocean
Ground
Tracked Combat Vehicles
General Dynamics Land Systems | BAE Systems | American Rheinmetall Vehicles | Textron Systems | McQ | General Dynamics Land Systems
Wheeled Combat Vehicles
General Dynamics Land Systems | General Dynamics Land Systems | AM General | BAE Systems | Navistar Defense | Oshkosh / FLYER Defense | Polaris Defense
Logistics, Engineering, and Support Vehicles
Oshkosh Defense | AM General | General Dynamics | DRS Technologies | Elbit Systems of America
Unmanned Ground Vehicle Hardware
QinetiQ North America | Pratt Miller Defense | HDT Global | Teledyne FLIR Defense | Howe & Howe | American Rheinmetall Vehicles | Swarmbotics AI | Chaos Industries | ACS | Aurelius
Ground Vehicle Autonomy Software and AI
Overland AI | Forterra | Anduril Industries | Palantir Technologies | Kodiak Robotics | Applied Intuition | Scale AI | Neya Systems | Scout AI | Shield AI | Gecko Robotics
Counter UAS and Directed Energy
Epirus | Raytheon/RTX | Northrop Grumman | Boeing/Kratos | L3Harris | SRC Inc.
Weapons, Fire Control, and Turret Systems
Northrop Grumman | BAE Systems | Elbit Systems of America | Leonardo DRS | Kongsberg
Vehicle Electronics, Survivability, and Subsystems
Leonardo DRS | Curtiss-Wright Defense | Cubic Defense | Wavelength Electronics / SY Coleman | FLIR Systems | Elbit Systems of America | Rafael Advanced Defense Systems | Artis LLC / Raytheon
Emerging Companies to Watch
FieldAI Federal | Allen Control Systems | Sarcos Robotics | Boston Dynamics | Ghost Robotics | Joby / Archer / Wisk | Absci | Istari
Space
Launch Vehicles and Launch Services
SpaceX | United Launch Alliance | Northrop Grumman | Rocket Lab | Firefly Aerospace | Relativity Space | True Anomaly | Apex | Stoke Space | Impulse Space
Large and Strategic Satellites
Lockheed Martin | Northrop Grumman | Boeing | L3Harris | Raytheon | Axiom Space | Sierra Space | Voyager Space | K2 Space
Small Satellites and Small Sat Buses
L3Harris | Millennium Space Systems | York Space Systems | Rocket Lab | Loft Orbital | Apex | Starfish Space | Terrain Orbital | Turion Space
Space Domain Awareness and Space Control
Lockheed Martin | L3Harris | Northrop Grumman | True Anomaly | Turion Space | LeoLabs | Slingshot Aerospace | Starfish Space | Rendezvous Robotics
Satellite Communications (SATCOM)
SpaceX (Starlink) | Northrop Grumman | L3Harris | Hughes | Viasat | Astranis | Northwood Space | Quantum Space
Space Intelligence, Surveillance and Reconnaissance (ISR)
Lockheed Martin | Northrop Grumman | Boeing | L3Harris | ICEYE | Spire Global | Kepler Communications | Varda Space Industries | EraDrive
Ground Systems, Command and Control (C2)
Lockheed Martin | Northrop Grumman | L3Harris | Boeing | SAIC | Leidos | Slingshot Aerospace | Northwood Space
Space Propulsion and In-Space Mobility
Northrop Grumman | Aerojet Rocketdyne (L3Harris) | Impulse Space | Ursa Major | Stoke Space | Turion Space | Starfish Space | Rendezvous Robotics
Munitions
Missiles and Precision Strike
RTX / Raytheon | Lockheed Martin | Northrop Grumman | Boeing | BAE Systems | L3Harris / Aerojet Rocketdyne | Anduril Industries | Castelion | Mach Industries | Firehawk Aerospace | Perseus Defense
Loitering Munitions and Kamikaze Drones
Anduril Industries | AeroVironment | Textron Systems | L3Harris | Kratos Defense | Mach Industries | DarkHive | Brinc Drones | Joby / Archer
Rockets, Mortars and Artillery
Northrop Grumman Innovation Systems | BAE Systems | General Dynamics Ordnance & Tactical Systems | Elbit Systems of America | Leonardo DRS | X-Bow Systems | Ursa Major | Firehawk Aerospace
Bombs, Warheads and Air-Delivered Munitions
RTX / Raytheon | Boeing | Lockheed Martin | Northrop Grumman | General Dynamics Ordnance & Tactical Systems | BAE Systems | L3Harris / Aerojet Rocketdyne
Solid Rocket Motors and Propellants
Northrop Grumman Innovation Systems | Aerojet Rocketdyne (L3Harris) | X-Bow Systems | Ursa Major | Firehawk Aerospace | Galodyne | Impulse Space
Torpedoes and Undersea Munitions
RTX / Raytheon | Northrop Grumman | Leonardo DRS | L3Harris | BAE Systems | Kongsberg | Oceaneering
Small Caliber Ammunition and Ground Weapons
General Dynamics Ordnance & Tactical Systems | BAE Systems | Olin / Winchester | Nammo | OSA Defense | True Velocity | PCP Ammunition
Directed Energy and Non-Kinetic Weapons
RTX / Raytheon | Northrop Grumman | Lockheed Martin | Boeing | L3Harris | Epirus | SRC Inc. | Kratos Defense
Missile Defense and Interceptors
RTX / Raytheon | Lockheed Martin | Northrop Grumman | Boeing | L3Harris | BAE Systems | Leidos
Munitions Supply Chain, Energetics and Raw Materials
Olin Corporation | American Pacific Corporation | Chemring Group | Nammo | Explosia | Maxeon | True Velocity
Munitions Autonomy, Guidance and Seekers
RTX / Raytheon | Northrop Grumman | L3Harris | Anduril Industries | Shield AI | Elbit Systems of America | Leonardo DRS | Applied Intuition
Advanced and Additive Manufacturing
Defense-Focused Contract and Advanced Manufacturing
Hadrian | General Atomics | TransDigm Group | HEICO | Ducommun | Mach Industries | Firestorm | Cambium | Deterrence
Additive Manufacturing and 3D Printing
Stratasys | 3D Systems | Relativity Space | Elementum 3D | Velo3D | Machina Labs | Firehawk Aerospace | Galodyne
Munitions and Energetics Manufacturing
Northrop Grumman Innovation Systems | Aerojet Rocketdyne (L3Harris) | Olin / Winchester | General Dynamics Ordnance & Tactical Systems | BAE Systems | X-Bow Systems | Firehawk Aerospace | Mach Industries | Castelion
Propulsion and Rocket Motor Manufacturing
Northrop Grumman Innovation Systems | GE Aerospace | Pratt & Whitney | Ursa Major | X-Bow Systems | Firehawk Aerospace | Galodyne | Impulse Space
Electronics, Semiconductors and Advanced Components
RTX | L3Harris | Leonardo DRS | Curtiss-Wright Defense | MACOM | Wolfspeed | Axcelis Technologies | Epirus
Shipbuilding and Naval Manufacturing
HII | General Dynamics NASSCO | General Dynamics Electric Boat | Austal USA | Fincantieri | BWX Technologies | VT Halter Marine | Metal Shark
Digital Manufacturing, AI and Production Automation
Palantir | Anduril | Machina Labs | Hadrian | Firestorm | Cambium | Istari | Mach Industries
Maintenance, Repair and Overhaul (MRO)
Lockheed Martin | Boeing | L3Harris | HEICO | TransDigm Group | Ducommun | Gecko Robotics | SAIC
Energy and Materials
Critical Minerals and Raw Materials
KoBold Metals | Vulcan Elements | Mariana Minerals | MP Materials | Energy Fuels | USA Rare Earth | Durin
Advanced Materials and Manufacturing Inputs
General Matter | Inertia | Sila | Unlimited Industries | Hexcel | Toray Composite Materials | Cytec Solvay
Nuclear Energy and Power
BWX Technologies | Kairos Power | Oklo | X-Energy | TerraPower | Last Energy | NuScale Power
Tactical and Expeditionary Power
Leonardo DRS | General Dynamics | Curtiss-Wright Defense | Exowatt | Aetherflux | BASE | Palantir
Energy Storage and Batteries
Sila | EaglePicher Technologies | Epsilor | Ultralife Corporation | EnerSys | Leonardo DRS
Fuel, Synthetic Fuels and Alternative Propellants
Boom Supersonic | Infinium | Prometheus Fuels | HIF Global | RCF Fuels | GE Aerospace | Pratt and Whitney
Space-Based and Beamed Energy
Aetherflux | Exowatt | Northrop Grumman | Lockheed Martin | Quaise Energy
Grid, Infrastructure and Energy Resilience
Leidos | SAIC | Parsons Corporation | Jacobs | BASE | BWX Technologies | Epirus
AI/ML
AI Platforms, Decision Support and Command and Control
Palantir | Anduril Industries | Lockheed Martin | Northrop Grumman | L3Harris | Leidos | SAIC | Vannevar Labs | Onebrief | Sandtable | Defcon AI | Nominal
Frontier AI and Large Language Models
OpenAI | Google | xAI | Anthropic| Microsoft | Meta AI
Autonomous Systems and Robotics AI
Shield AI | Applied Intuition | Overland AI | Forterra | Kodiak Robotics | Reliable Robotics | Scout AI | Dominion Dynamics | Fivecast | Air Space Intelligence
Intelligence, Surveillance and Reconnaissance AI
Palantir | Leidos | Vannevar Labs | BigBear.ai | Modern Intelligence | NODA | Schemata | Primordial Labs | Legion | Axion Ray
Geospatial AI and Earth Observation Analytics
DroneDeploy | Maxar Technologies | Planet Labs | BigBear.ai | GA Vibit | Fivecast | ICEYE | Spire Global
Mission Planning and Tactical Applications
TurbineOne | Beacon AI | Gallatin | Kestrel Intelligence | Breaker | Rune | Dungeon AI | Pytho | Lumbra | Rohirrim
AI-Enabled Cybersecurity and Threat Detection
Darktrace | CrowdStrike | Leidos | Code Metal | Foxglove | Edgerunner AI | Pryzm | IronFlow AI
AI Infrastructure, Data and MLOps
Scale AI | Microsoft | Amazon Web Services | Google Cloud | Oracle | Helios | Flock Safety
Simulation, Synthetic Data and AI Training Environments
Scale AI | Istari | Northrop Grumman | Lockheed Martin | Sandtable | Primordial Labs | Applied Intuition | Bohemia Interactive Simulations
Business and Enterprise AI Applications
Palantir | Code Metal | Onebrief | Axion Ray | Pryzm | IronFlow AI | Edgerunner AI | Rohirrim | Helios
Cyber
Cybersecurity Platforms and Enterprise Defense
Leidos | SAIC | Booz Allen Hamilton | ManTech | L3Harris | Northrop Grumman | Raytheon | Second Front Systems | Shift5 | CrowdStrike | Palo Alto Networks
Offensive Cyber and Cyber Operations
Northrop Grumman | Leidos | Booz Allen Hamilton | SAIC | Enabled Intelligence | TRM Labs | Defense Unicorns | Bastille
Operational Technology and Industrial Control System Security
Dragos | Claroty | Nozomi Networks | SAIC | Leidos | Picogrid | Shift5 | Parsons Corporation
Zero Trust, Identity and Access Management
Virtru | Arkenstone | Okta | Zscaler | BeyondTrust | Booz Allen Hamilton | Moonify
Secure Communications and Data Encryption
Virtru | L3Harris | Northrop Grumman | General Dynamics Mission Systems | Viasat | TRM Labs | Bastille | Arkenstone
Software Defined Infrastructure and Cloud Security
Second Front Systems | Defense Unicorns | Picogrid | OpenInfer | WebAI | Microsoft | Amazon Web Services | Oracle
RF, Wireless and Electromagnetic Spectrum Security
Bastille | L3Harris | Northrop Grumman | RTX | Viasat | Epirus | SRC Inc.
Computer Vision, Sensor Fusion and Data Analytics
Voxel51 | OpenInfer | Palantir | Leidos | Scale AI | WebAI | Moonify | Elbit Systems of America
Critical Infrastructure Protection
Dragos | Claroty | Parsons Corporation | Leidos | SAIC | Booz Allen Hamilton | Jacobs | Flock Safety
Communications
Tactical Communications and Radios
L3Harris | Northrop Grumman | BAE Systems | General Dynamics Mission Systems | Viasat | Collins Aerospace | Rebellion | Dominion Dynamics
Satellite Communications and Space-Based Connectivity
SpaceX (Starlink) | Viasat | L3Harris | Hughes | Armada | Astranis | Northwood Space | Collins Aerospace
Edge Computing and Deployed Processing
Armada | Defense Unicorns | Second Front Systems | Rebellion | Leidos | SAIC | Picogrid | Palantir
Spectrum, Electronic Warfare and Signals Intelligence
Northrop Grumman | L3Harris | RTX | BAE Systems | Bastille | Mesa Quantum | SRC Inc. | Epirus | Bandelier
ISR, Sensing and Persistent Surveillance
Hidden Level | HawkEye 360 | World View | Emesent | Aalyria | Leidos | Northrop Grumman | L3Harris
Autonomous and Aerial ISR Platforms
World View | Emesent | Hidden Level | General Atomics ASI | Northrop Grumman | Shield AI | Skydio | Dominion Dynamics
Quantum Communications and Positioning, Navigation and Timing
Mesa Quantum | Northrop Grumman | Lockheed Martin | L3Harris | RTX | IonQ | Quantinuum | SBQuantum
Network Management, Resilience and JADC2
Lockheed Martin |Northrop Grumman | Leidos | SAIC | Aalyria | Anduril Industries | Palantir | Viasat | Aalyria
The Five Major Prime Contractors of the Defense Industry
Defense Industry

Source: Defense News Top 100
2024 Defense Revenue
After the top 5, there's a significant drop off to the second tier of companies rounding out the top 10.

The U.S. has 48 of the Top 100 defense companies in the world based on 2024 defense revenue. This chart plots the 2024 defense revenue for all 48 companies showing the outsized impact the primes have in market capture.


Defense Prime Consolidation
The defense industry saw a massive consolidation in the 1980s and 1990s with five major prime contractors dominating the market share of defense contracts. This consolidation was accelerated following a Last Supper dinner in 1993 hosted by SECDEF Les Aspen and DEPSECDEF William Perry with defense executives.

Source: NASA Commission on the Future of U.S. Aerospace Industry Report
Keep in mind, it is often discussed and reported that DoD consolidated from 51 primes to five. The above chart shows the lineage of 51 companies to the five biggest primes, but that's not to suggest there are only five primes. As you'll see in the next section below, L3Harris, HII, and Leidos, along with dozens of other companies are doing billions of dollars of defense work as primes. There are also emerging non-traditional defense companies capturing prime roles on contracts.
As Dr. Jerry McGinn noted in a recent article, "Since 2000, the overall shape of the industrial base has stayed remarkably consistent with five major primes, around 100 tier 1 and tier 2 mid- to large-sized firms that serve as primes or subcontractors on various programs, and thousands of small businesses."
Shyam Sankar, Madeline Zimmerman, and Greg Little have a First Breakfast Substack championing a renewal of the industrial base to reverse the effects of the Last Supper.
Largest U.S. Defense Contractors
The United States has 47 of the world's top 100 defense companies. This table is ranked by defense revenue in 2024.
- As you can see the five major primes are in the first tier, with a clear drop off between Boeing at $31.7B and L3 Harris at $16.9B.
- There is a wide mix of "pure defense companies" that get most of their revenue from defense like Lockheed Martin (96%), HII (!00%), and SNC (97%) and companies that have a majority of revenue from outside defense like Boeing (48%), GE Aerospace (16%), and Honeywell (18%).
- The list includes two companies that manage FFRDCs, MITRE (31) and Aerospace (36).
- For the first time, this list includes venture backed, non-traditional defense companies, SpaceX (18), Palantir (30), and Anduril (43).
| US Rank | Global Rank | Company | Total revenue for 2024 | Total defense revenue for 2024 | Revenue From Defense |
|---|---|---|---|---|---|
| 1 | 1 | Lockheed Martin | $71,043,000,000 | $68,390,000,000 | 96% |
| 2 | 2 | RTX | $80,700,000,000 | $43,500,000,000 | 54% |
| 3 | 4 | Northrop Grumman | $41,000,000,000 | $36,600,000,000 | 89% |
| 4 | 5 | General Dynamics | $47,716,000,000 | $36,500,000,000 | 76% |
| 5 | 7 | Boeing | $66,517,000,000 | $31,750,000,000 | 48% |
| 6 | 9 | L3Harris | $21,325,000,000 | $16,982,000,000 | 80% |
| 7 | 15 | Leidos | $16,662,000,000 | $11,558,152,000 | 69% |
| 8 | 16 | HII | $11,535,000,000 | $11,527,000,000 | 100% |
| 9 | 17 | Amentum | $13,858,000,000 | $8,488,000,000 | 61% |
| 10 | 19 | Booz Allen Hamilton | $11,979,596,000 | $7,809,889,000 | 65% |
| 11 | 20 | CACI International | $8,132,449,000 | $7,266,596,000 | 89% |
| 12 | 23 | GE Aerospace | $38,708,000,000 | $6,109,000,000 | 16% |
| 13 | 24 | Honeywell | $34,498,000,000 | $6,091,000,000 | 18% |
| 14 | 30 | KBR | $7,742,000,000 | $4,968,400,000 | 64% |
| 15 | 33 | ATI | $4,823,111,746 | $4,685,356,085 | 97% |
| 16 | 34 | Peraton | $6,974,300,000 | $4,376,600,000 | 63% |
| 17 | 39 | Parsons | $6,800,000,000 | $4,007,100,000 | 59% |
| 18 | 40 | SpaceX | $13,100,000,000 | $4,000,000,000 | 31% |
| 19 | 41 | V2X | $4,322,155,000 | $3,921,271,000 | 91% |
| 20 | 42 | SAIC | $7,479,000,000 | $3,873,000,000 | 52% |
| 21 | 45 | Textron | $13,702,000,000 | $3,370,000,000 | 25% |
| 22 | 46 | TransDigm | $8,157,000,000 | $3,262,800,000 | 40% |
| 23 | 48 | Bechtel National | $23,000,000,000 | $3,080,000,000 | 13% |
| 24 | 56 | Oshkosh | $10,730,200,000 | $2,155,200,000 | 20% |
| 25 | 58 | BWX Technologies | $2,703,654,000 | $2,095,900,000 | 78% |
| 26 | 61 | Viasat | $4,519,600,000 | $2,039,100,000 | 45% |
| 27 | 63 | Sierra Nevada Corp. | $2,000,000,000 | $1,940,000,000 | 97% |
| 28 | 65 | Parker Hannifin | $19,900,000,000 | $1,879,000,000 | 9% |
| 29 | 66 | Curtiss-Wright | $3,121,000,000 | $1,792,000,000 | 57% |
| 30 | 70 | Palantir | $2,866,000,000 | $1,574,000,000 | 55% |
| 31 | 73 | MITRE | $2,469,000,000 | $1,453,000,000 | 59% |
| 32 | 74 | Moog | $3,609,159,573 | $1,394,776,700 | 39% |
| 33 | 75 | ManTech | $3,100,000,000 | $1,300,000,000 | 42% |
| 34 | 76 | HEICO | $3,858,000,000 | $1,298,000,000 | 34% |
| 35 | 81 | Howmet Aerospace | $7,400,000,000 | $1,184,000,000 | 16% |
| 36 | 83 | Aerospace Corporation | $1,365,022,000 | $1,158,938,000 | 85% |
| 37 | 85 | Keysight Technologies | $5,007,000,000 | $1,157,000,000 | 23% |
| 38 | 86 | TTM Technologies | $2,442,753,000 | $1,127,529,000 | 46% |
| 39 | 89 | Teledyne Technologies | $5,670,000,000 | $1,062,700,000 | 19% |
| 40 | 90 | StandardAero | $5,228,421,053 | $993,400,000 | 19% |
| 41 | 91 | Kratos Defense | $1,136,300,000 | $988,700,000 | 87% |
| 42 | 92 | Spirit AeroSystems | $6,317,000,000 | $975,200,000 | 15% |
| 43 | 93 | Anduril | $1,000,000,000 | $950,000,000 | 95% |
| 44 | 94 | M1 Support Services | $900,000,000 | $900,000,000 | 100% |
| 45 | 96 | Mercury Systems | $833,075,000 | $833,075,000 | 100% |
| 46 | 99 | AM General | $740,000,000 | $740,000,000 | 100% |
| 47 | 100 | Hexcel Corporation | $1,900,000,000 | $703,000,000 | 37% |
Source: Defense News Top 100 for 2025
Largest U.S. Defense Contractors by Market Cap
- Palantir $435B
- RTX $227B
- Boeing $171B
- Honeywell $133B
- Lockheed Martin $120B
- Parker-Hannifin $95B
- General Dynamics $93B
- Northrop Grumman $91B
- TransDigm $72B
- L3 Harris $57B
- Leidos $25B
- Curtiss-Wright $21B
- AeroVironment $20B
- Kratos Defense $18B
- Textron $15B
- Booz Allen Hamilton $13B
- Leonardo DRS $12B
- CACI $12B
- HII $11B
- Parsons $9B
- Amentum $6B
- KBR $6B
- Mercury Systems $5B
- SAIC $5B
- ViaSat $5B
- Spirit AeroSystems $5B
- ManTech $4B
- VSE Corporation $3B
- Voyager Technologies $2B
- V2X $2B
As of Oct 8, 2025
Source: Companies Market Cap
Defense Tech Company Financials
Defense Technology Companies have had strong stock growth and EBITDA valuation multiples relative to other sectors.
- Defense Technology Companies include: AeroVironment, Curtiss-Wright, Kratos Defense, Leonardo DRS, Mercury Systems, Palantir Technologies, Teledyne Technologies, and Textron.
- Multiple Platform Contractors include: Boeing, General Dynamics, General Electric, Honeywell, Huntington Ingalls Industries, L3 Harris, Lockheed Martin, Northrop Grumman, and RTX.
- Government Services include: Amentum Holdings, Booz Allen Hamilton, CACI International, ICF International, Leidos Holdings, Parsons, SAIC, and V2X
- Space and Satellite include: BlackSky Tech, Intuitive Machines, Iridium Communications, Karman Holdings, Planet Labs, Redwire, Rocket Lab, Spire Global, Viasat, Voyager Tech

Source: Raymond James Defense & Government Market Intel Report, Sep 2025


Source: Breaking Defense leveraging McAleese and Associates data.
Buybacks and Dividends
On January 7, 2026, the White House issued a sweeping Executive Order (EO) titled Prioritizing the Warfighter in Defense Contracting, which marks a profound shift from a shareholder-first financial model to a production-first model.
While the government has been a terrible customer these last few years by not providing steady demand signals to build confidence in these investments, the data shows this is only part of the problem.
Raytheon
- RTX (Raytheon) is currently sitting on a $251B backlog, yet it takes upwards of 24 months to secure parts for a single Patriot radar unit.
- The “Big Five” are failing across every major strategic domain.
- Lockheed Martin: The F-35 TR-3/Block 4 upgrade is five years behind schedule and $6B over budget.
- General Dynamics: Submarine production is stuck at 1.2 boats annually against a requirement for 2.0.
- Northrop Grumman: The Sentinel ICBM program is 81% over budget ($141B total) and years behind schedule.
- The government's new stance is simpler: if you have the balance sheet capacity to fund a $10B accelerated buyback during a technical crisis (as RTX did in 2023) you have the capacity to fix your own production lines without a taxpayer bailout.
- RTX has returned over $44B to shareholders through dividends and buybacks, more than 3X its investment in manufacturing (CapEx) over the same period.

Lockheed Martin
- Lockheed Martin represents the pinnacle of this “financialized” defense model.
- The company has not only paid dividends for over 40 years but has increased that dividend for 23 consecutive years.
- This streak became a sacred cow for institutional investors, but it created an impossible internal hurdle for management - as it becomes it becomes near-impossible to reallocate capital toward long-term, risky industrial projects without decimating the stock price.

- The forced pivot to CapEx is a massive tailwind for the sub-tier supply chain. When RTX is forced to spend $5B on “industrial capacity” instead of buybacks, that money flows to advanced manufacturing, robotics, and energetic suppliers.
- Advanced Manufacturing: Firms providing automated composite layup and 3D-printing for aerospace will see a surge in orders.
- Defense-Tech Startups: Smaller, more nimble firms can now partner with primes who are suddenly desperate to show “production innovation” to the Pentagon to get their dividend licenses back.
- Domestic Sourcing: The “Golden Dome” missile shield and other 2026 supplemental bills favor companies that have already invested in American jobs rather than offshore arbitrage.


Before, any defense tech start-up aimed at solving a pain point or bottleneck for a prime would have a hard time getting a meeting with their corporate venture teams, but after this announcement, expect to see a flurry of activity out of these entities.
Our Take
While there are some egregious examples that show the primes not taking their responsibilities seriously enough, it's too simplistic to place the blame only at the feet of the primes. DoD built this system that rewards low-risk behaviors (cost-plus contracts and reimbursable IR&D) coupled with very low profit margins. This system forced defense contractors who get most of their funding from the government to adapt and reward shareholders in the best way possible. Corporate compensation boards structured executive incentives around efficient execution, cash flow, and work backlog which rent-seeking investment funds rewarded. There was no reward for huge outlays of cash towards expanded manufacturing that the government may not place orders against or change its mind in one year (which happened often). So, while this shift is desperately needed and defense primes need to adjust their risk calculus, DoW will have to reward big investments (not just with the primes but new entrants too) with some degree of stability. The multi-year contracts approved in the FY26 NDAA go a long way. Dependence on reconciliation dollars does not however and maxed out SM-6 orders in FY26 can't lead to min sustainment rate orders in FY27! FYI - the $1.5T FY27 superbudget is contingent on another reconciliation package.
Source: Industrial Base Alpha
Executive Order: Prioritizing the Warfighter in Defense Contracting
In January 2026, President Trump signed an executive order:
- While the U.S. produces the best military equipment in the world, we do not make enough of it quickly enough to meet the needs of our military and our partners.
- It is imperative that our defense contractors be held to the highest standards intended to ensure the advancement of core national interests.
- Many large contractors - while underperforming on existing contracts - pursue newer, more lucrative contracts, stock buy-backs, and excessive dividends to shareholders at the cost of production capacity, innovation, and on-time delivery.
- Effective immediately, they are not permitted to pay dividends or buy back stock, until such time as they are able to produce a superior product, on time and budget.
- It is the policy of the U.S. Government to accelerate defense procurement and revitalize the defense industrial base to maintain peace through strength.
Buy Backs and Dividends
- Major defense contractors will no longer conduct stock buy-backs or issue dividends at the expense of accelerated procurement and increased production capacity.
- SECWAR shall identify any defense contractors that engaged in any stock buy-back or corporate distribution while:
- underperforming on their contracts
- not investing their own capital into necessary production capacity
- not sufficiently prioritizing U.S. Government contracts
- having insufficient production speed
- When the contractor's remediation plan is insufficient, the SECDEF may initiate immediate actions to secure remedies that will expedite production, prioritize the U.S. military, and return the contractor to sufficient performance, investment, prioritization, and production, to the maximum extent permitted by law.
- Within 60 days, DoW shall ensure that any future contract with any new or existing defense contractor, including any renewal, contains a provision prohibiting both any stock buy-back and corporate distributions.
Future Contracts
- Future contracts shall stipulate that executive incentive compensation for contractors will not be tied to short-term financial metrics, such as free cash flow or earnings per share driven by stock buy-backs and instead will be linked to on-time delivery, increased production, and facilitation required to rapidly expand our U.S. stockpiles and capabilities.
- SECWAR in consultation with State and Commerce shall consider whether it is appropriate to deny advocacy for underperforming contractors to compete in FMS or DCS.
Non-Traditional Defense Contractor
A nontraditional defense contractor, with respect to a procurement or with respect to a transaction authorized under section 4021(a) or 4022 of this title, means an entity that is not currently performing and has not performed, for at least the one-year period preceding the solicitation of sources by the Department of Defense for the procurement or transaction, any contract or subcontract for the Department of Defense that is subject to full coverage under the cost accounting standards prescribed pursuant to section 1502 of title 41 and the regulations implementing such section.
10 USC 3014
Exemptions for Nontraditional Defense Contractors
Per FY26 NDAA Sec. 1826. Exemptions for Nontraditional Defense Contractors
- DFARS 252.242-7006. Cost Accounting System
- DFARS 252.234-7002. EVMS
- DFARS 252.215-7002. Cost Estimating System
- DFARS 252.242-7004 Material Management and Accounting System
- DFARS 252.245-7003 Contractor Property Management System Administration
- DFARS 252.244-7001 Contractor Purchasing System Administration
- DFARS 252.242-7005 Contractor Business Systems
- DFARS 215.407 Special Cost or Pricing Areas
- 10 USC 3702 Required cost or pricing data and certification
- FAR Part 31 Contract Cost Principles and Procedures
The requirements may bewaived or modified with a written determination approved by the head of the relevant contracting activity. May only be delegated to a senior contracting official or a more senior official. The justification must explain why application of such requirements is in the best interest of the federal government.
10 USC 3457
Treatment of certain products and services as commercial products and commercial services
(a) Goods and Services Provided by Nontraditional Defense Contractors.-Notwithstanding section 3451(1) of this title, products and services provided by nontraditional defense contractors (as that term is defined in section 3014 of this title) may be treated by the head of an agency as commercial products and commercial services, respectively, for purposes of this chapter.
(b) Services Provided by Certain Nontraditional Contractors.-Notwithstanding section 3451(1) of this title, services provided by a business unit that is a nontraditional defense contractor (as that term is defined in section 3014 of this title) shall be treated as commercial services for purposes of this chapter, to the extent that such services use the same pool of employees as used for commercial customers and are priced using methodology similar to methodology used for commercial pricing.(c) Commingled Items Purchased by Contractors.-Notwithstanding section 3451(1) of this title, items valued at less than $10,000 that are purchased by a contractor for use in the performance of multiple contracts with the Department of Defense and other parties and are not identifiable to any particular contract shall be treated as a commercial product for purposes of this chapter.
Source: 10 USC 3457
Note: During the FY26 NDAA there was a draft provision and debate to change this language from NDCs "may be treated" as commercial to "shall be treated". That did not make the final bill, so treating NDC products and services as commercial remains subject to the contracting officer and acquiring organization's discretion.
Class Deviation 2026-O0028 - DFARS Part 212
Class Deviation 2026-O0028 - Revolutionary Federal Acquisition Regulation (FAR) Overhaul Part 12, Defense FAR Supplement (DFARS) Part 212 (18 December 2025)
 Attachment 1, Class Deviation 2026-O0028 - Revolutionary Federal Acquisition Regulation (FAR) Overhaul Part 12, Defense FAR Supplement (DFARS) Part 212 (18 December 2025)
- DFARS Part 212 Line Out (18 December 2025)
- Attachment 2, Class Deviation 2026-O0028 - Revolutionary Federal Acquisition Regulation (FAR) Overhaul Part 12, Procedures, Guidance, and Information (PGI) 212 (18 December 2025)
Acquisition of Commercial Products and Commercial Services (Effective February 1, 2026)
This is the primary deviation. It implements two statutory authorities side-by-side under DFARS 212.102(a):
Authority 1 - 10 U.S.C. 3457 (Discretionary): Contracting officers maytreat supplies and services provided by nontraditional defense contractors as commercial products or commercial services. This permissive authority is intended to enhance defense innovation and investment, enable DoD to acquire items that otherwise might not have been available, and create incentives for nontraditional defense contractors to do business with DoD. The decision does not require a commercial product or commercial service determination and does not mean the item is actually commercial.
Authority 2 - 10 U.S.C. 3457 (Mandatory): Contracting officers shalltreat services provided by a business unit that is a nontraditional defense contractor as commercial services, to the extent that such services use the same pool of employees as used for commercial customers and are priced using methodology similar to methodology used for commercial customers.
Documentation Requirement: Contracting officers shall document the file when treating supplies or services from a nontraditional defense contractor as commercial products or commercial services.
The War Unicorns
Venture Backed Defense Tech Startups Worth over $1B
See Our Substack Piece from Nov 2025
The War Unicorns
- Palantir Technologies (post-IPO): Gotham and Foundry platforms for intel fusion and targeting.
- Anduril Industries: Lattice AI for border and base defense, unmanned aerial systems, and counter-UAS.
- Saronic Technologies: Autonomous surface vessels for naval ops.
- Shield AI: Hivemind AI for drone swarms in GPS-denied zones.
- Skydio: Enterprise drones with 360° obstacle avoidance.
- Applied Intuition: Autonomous vehicle simulation and testing for defense applications.
- Scale: Data labeling and AI infrastructure for training defense ML models.
- Govini: AI analytics for supply chain and acquisition optimization.
- Vannevar Labs: Open-source intel tools for threat hunting.
- Forterra: Autonomy platform for vehicles, robotic swarms, and mission systems
Top 100 Defense Tech Companies by Funds Raised
| Company | Category | Funds Raised | Founded | |
| 1 | SpaceX | Space | SpaceX | 2002 |
| 2 | Databricks | Defense SaaS & AI | Defense SaaS & AI | 2013 |
| 3 | Archer Aviation | Aerospace | Archer Aviation | |
| 4 | Relativity Space | Space | Space | 2015 |
| 5 | Anduril | Autonomy | Autonomy | 2017 |
| 6 | Sierra Space | Space | Space | 2021 |
| 7 | Automation Anywhere | Defense SaaS & AI | Defense SaaS & AI | 2003 |
| 8 | SambaNova Systems | Defense SaaS & AI | SambaNova Systems | 2017 |
| 9 | Shield AI | Autonomy | Shield AI | 2015 |
| 10 | Rubrik | Defense SaaS & AI | Rubrik | 2014 |
| 11 | DataRobot | Defense SaaS & AI | Defense SaaS & AI | 2012 |
| 12 | Zipline | Unmanned Aircraft Systems (UAS) | Zipline | 2016 |
| 13 | Dataiku | Defense SaaS & AI | Defense SaaS & AI | 2013 |
| 14 | Carebras Systems | Defense SaaS & AI | Defense SaaS & AI | 2015 |
| 15 | Skydio | UAS | UAS | 2014 |
| 16 | Astranis | Space | Space | 2015 |
| 17 | Flock Safety | Public Safety | Public Safety | 2017 |
| 18 | ThoughtSpot | Defense SaaS & AI | ThoughtSpot | 2012 |
| 19 | PsiQuantum | Miscellaneous | PsiQuantum | 2016 |
| 20 | Axiom Space | Space | Space | 2016 |
| 21 | Scale AI | Defense SaaS & AI | Scale AI | 2016 |
| 22 | Grafana Labs | Miscellaneous | Miscellaneous | 2014 |
| 23 | Kymeta | Space | Space | 2012 |
| 24 | ABL Space Systems | Space | Space | 2017 |
| 25 | Blue Origin | Space | Space | 2000 |
| 26 | SandboxAQ | Miscellaneous | SandboxAQ | 2022 |
| 27 | Firefly Aerospace | Space | Space | 2017 |
| 28 | CloudBees | Defense SaaS & AI | Defense SaaS & AI | 2010 |
| 29 | ICON | Manufacturing | Manufacturing | 2017 |
| 30 | Hawkeye 360 | Space | Space | 2015 |
| 31 | Momentus | Space | Space | 2017 |
| 32 | Whoop | Miscellaneous | Whoop | 2011 |
| 33 | Dragos | Defense SaaS & AI | Dragos | 2016 |
| 34 | Applied Intuition | Defense SaaS & AI | Defense SaaS & AI | 2017 |
| 35 | Spark Cognition | Defense SaaS & AI | Spark Cognition | 2013 |
| 36 | Velo3D | Manufacturing | Velo3D | 2014 |
| 37 | Versa Networks | Defense SaaS & AI | Versa Networks | 2009 |
| 38 | Blacksky | Space | Space | 2013 |
| 39 | Epirus | Counter-UAS | Epirus | 2018 |
| 40 | Boom Supersonic | Aerospace | Boom Supersonic | 2014 |
| 41 | Ursa Major | Hypersonics | Ursa Major | 2015 |
| 42 | Capella Space | Space | Space | 2016 |
| 43 | Spaceflight Industries | Space | Spaceflight Industries | 2009 |
| 44 | Vast Data | Defense SaaS & AI | Vast Data | 2016 |
| 45 | Interos | Defense SaaS & AI | Interos | 2005 |
| 46 | Astra | Space | Space | |
| 47 | Mirantis | Defense SaaS & AI | Mirantis | 1999 |
| 48 | Formlabs | Manufacturing | Manufacturing | 2011 |
| 49 | Formlogic | Manufacturing | Manufacturing | 2011 |
| 50 | Primer | Defense SaaS & AI | Primer | 2014 |
| 51 | Forterra (RRAI) | Autonomy | Forterra (RRAI) | 2002 |
| 52 | Rebellion Defense | Defense SaaS & AI | Rebellion Defense | 2019 |
| 53 | Gecko Robotics | Autonomy | Gecko Robotics | 2013 |
| 54 | Hadrian | Manufacturing | Manufacturing | |
| 55 | 6K | Miscellaneous | Miscellaneous | 2014 |
| 56 | Lyten | Miscellaneous | Miscellaneous | 2015 |
| 57 | Federated Wireless | Communication | Federated Wireless | 2012 |
| 58 | Uveye | Manufacturing | Uveye | 2016 |
| 59 | Swift Navigation | Miscellaneous | Swift Navigation | 2012 |
| 60 | BigID | Defense SaaS & AI | Defense SaaS & AI | 2016 |
| 61 | Fictiv | Manufacturing | Manufacturing | 2013 |
| 62 | Ayar Labs | Miscellaneous | Miscellaneous | 2015 |
| 63 | SiMa.ai | Defense SaaS & AI | SiMa.ai | 2018 |
| 64 | Saildrone | Maritime | Saildrone | 2012 |
| 65 | Infleqtion | Defense SaaS & AI | Infleqtion | 2007 |
| 66 | Spinlaunch | Space | Spinlaunch | |
| 67 | Voyager Space | Aerospace | Voyager Space | 2019 |
| 68 | Varda Space | Space | Varda Space | 2020 |
| 69 | Nozomi Networks | Defense SaaS & AI | Nozomi Networks | 2013 |
| 70 | Umbra | Space | Umbra | |
| 71 | Rescale | Defense SaaS & AI | Rescale | 2011 |
| 72 | Loft Orbital | Space | Space | 2017 |
| 73 | Kodiak Robotics | Autonomy | $165,000,000 | |
| 74 | Airspace Technologies | Aerospace | Airspace Technologies | 2016 |
| 75 | Snorkel | Defense SaaS & AI | Snorkel | 2015 |
| 76 | Dedrone | Counter-UAS | Dedrone | 2014 |
| 77 | True Anomaly | Space | True Anomaly | |
| 78 | Leolabs | Space | Space | 2016 |
| 79 | Albedo Space | Space | Space | 2020 |
| 80 | Hermeus | Hypersonics | Hypersonics | 2018 |
| 81 | Red6 | Red6 | 2018 | |
| 82 | Elroy Air | Aerospace | Elroy Air | |
| 83 | Shift5 | Defense SaaS & AI | Shift5 | 2019 |
| 84 | Percipient AI | Defense SaaS & AI | Percipient AI | |
| 85 | Vennevar Labs | Defense SaaS & AI | Vennevar Labs | 2019 |
| 86 | Slingshot Aerospace | Defense SaaS & AI | Slingshot Aerospace | 2017 |
| 87 | Cesium Astro | Communication | Communication | 2017 |
| 88 | Brinc | Public Safety | Public Safety | 2017 |
| 89 | Mach Industries | Munitions | Munitions | |
| 90 | GoTenna | Communication | GoTenna | |
| 91 | Second Front Systems | Defense SaaS & AI | Second Front Systems | 2014 |
| 92 | Impulse Space | Space | Space | 2021 |
| 93 | Stoke Space Technologies | Space | Stoke Space Technologies | 2019 |
| 94 | Privateer | Space | Space | |
| 95 | Saronic | Maritime | Saronic | |
| 96 | Chaos Industries | Miscellaneous | Miscellaneous | |
| 97 | Lambda Labs | Defense SaaS & AI | Lambda Labs | 2012 |
| 98 | Eclypsium | Defense SaaS & AI | Eclypsium | 2017 |
| 99 | Stellar Cyber | Defense SaaS & AI | Stellar Cyber | 2015 |
| 100 | Liquid Instruments | Miscellaneous | Miscellaneous | 2014 |
Source: Merging SVDG NATSEC 100 with AEON Analysis
NatSec 100
The Silicon Valley Defense Group publishes an annual ranking of the top 100 venture funded defense and dual use startups. It offers a data-driven snapshot of the evolving techno-security ecosystem.
- Raised: $70.1B in private capital (Up 32% from 2024)
- Federal Awards: $28.6B as a prime, sub, OTA, or SBIR/STTR (up 18% from 2024)
- $25.8B Prime
- $1.8B OTA
- $798M Subcontractor
- $199M SBIR
- Average Age: 8.3 years


Investment and Awards of Non-Traditional Defense Contractors
Most small businesses and startups are considered non-traditional companies. They may not have any defense contracts over $50M or if they do, they were firm-fixed price, or followed commercial procedures.
Startups
DoD is constantly seeking to leverage more startups and non-traditional defense contractors to regrow the shrinking industrial base. Former SECDEF Dr. Ash Carter established DIUx to tap Silicon Valley companies. Now called DIU, they have expanded to Boston, Austin, and Chicago. DIU has championed using a Commercial Solutions Opening to rapidly tap mature commercial technologies. DoD invests billions in Small Business Innovation Research (SBIR) - small research contracts to help companies mature technologies and shape applications to DoD needs. DoD is also leveraging more Other Transactions Authorities to rapidly establish agreements on research, prototypes, and even production contracts. While each of these efforts have mixed results, the objectives are to help small businesses grow, provide funding during early stages, focus developments on priority military needs/opportunities, and foster greater competition at each tier of the defense industry.
Venture Deals
Venture Capital deals continue strong growth. 2021 was the best year with nearly 18,000 deals for $344B. Source: Pitchbook.

Within defense tech, there continues to be a strong demand signal.
 Source:
Industry Analysis
State of Competition within the Defense Industrial Base
Source: State of Competition within the Defense Industrial Base, OUSD(A&S), Feb 2022
Since the 1990s, the defense sector has consolidated substantially, transitioning from 51 to 5 aerospace and defense prime contractors. As a result, DoD is increasingly reliant on a small number of contractors for critical defense capabilities. Consolidations that reduce required capability and capacity and the depth of competition would have serious consequences for national security. Over approximately the last three decades, the number of suppliers in major weapons system categories has declined substantially: tactical missile suppliers have declined from 13 to 3, fixed-wing aircraft suppliers declined from 8 to 3, and satellite suppliers have halved from 8 to 4. Today, 90% of missiles come from 3 sources. As a result, promoting competition and ensuring it is fair and open for future programs is a critical Department priority.

| Weapons Category | U.S. Based Prime Contractors |
| Tactical Missiles | Boeing, Lockheed Martin, Raytheon Technologies |
| Fixed Wing Aircraft | Boeing, Lockheed Martin, Northrop Grumman |
| Expendable Launch Vehicles | Boeing, Lockheed Martin |
| Satellites | Boeing, Hughes, Lockheed Martin, Northrop Grumman |
| Surface Ships | General Dynamics, Huntington Ingalls |
| Tactical Wheeled Vehicles | AM General, General Motors, Oshkosh |
| Tracked Combat Vehicles | General Dynamics |
| Strategic Missiles | Boeing, Lockheed Martin |
| Torpedoes | Lockheed Martin, Raytheon Technologies |
| Rotary Wing Aicraft | Bell Textron, Boeing, Lockheed Martin (Sikorsky) |
Updated DIB Competition Table
Manned Systems
| Capability Area | 1990 | 2024 |
| Aircraft | ||
| Fixed Wing | 8 | 4 |
| Rotary Wing | 4 | 3 |
| Ships | ||
| Surface | 8 | 4 |
| Submarines | 2 | 2 |
| Ground Vehicles | ||
| Wheeled | 6 | 6 |
| Tracked | 3 | 4 |
| Space Systems | ||
| Large Satellites | 8 | 4 |
| Launch | 2 | 3 |
| Missiles and Munitions | ||
| Strategic | 3 | 3 |
| Tactical | 13 | 3 |
| Torpedo | 3 | 2 |
Unmanned Systems
| Capability Area | 1990 | 2024 |
| Aircraft | ||
| Unmanned Aerial Systems (UAS) | 1 | > 44 |
| Ships | ||
| Unmanned Surface | - | 8 |
| Unmanned Underwater | - | 11 |
| Ground Vehicles | ||
| Unmanned Ground | - | 6 |
| Space Systems | ||
| Small Satellites | - | 11 |
Assessing and Strengthening the Manufacturing and Defense Industrial Base and Supply Chain Resiliency of the U.S
Major Findings
- Macro forces have led to impacts primarily in the sub-tiers of the defense supply chain
- A surprising level of foreign dependence on competitor nations exists;
- Workforce challenges face employers across all sectors; and
- Many sectors continue to move critical capabilities offshore in pursuit of competitive pricing and access to foreign markets.
Recommendations
The DoD-led Interagency Task Force recognizes ongoing efforts to address the challenges identified in the EO 13806 assessment, including:
- Increased near-term DoD budget stability with the passage of the Bipartisan Budget Act of 2018, providing stable funding through Fiscal Year (FY) 2019
- Modernization of the Committee on Foreign Investment in the U.S. and investigations under Section 301 of the Trade Act of 1974 into Chinese intellectual property theft, to better combat Chinese industrial policies targeting American intellectual property
- Updates to the Conventional Arms Transfer policy and unmanned aerial systems export policy to increase U.S. industrial base competitiveness and strengthen international alliances
- Reorganization of the former Office of the Under Secretary of Defense for Acquisition, Technology and Logistics, the work of the “Section 809 panel,” and development of the adaptive acquisition framework all aim to streamline and improve defense acquisition
processes - Restructuring the Defense Acquisition University to create a workforce education and training resource to foster increased agility in acquisition personnel
- Response to Section 1071(a) of the National Defense Authorization Act for FY2018 which requires establishing a process for enhancing the ability to analyze, assess, and monitor vulnerabilities of the industrial base
- Creation of a National Advanced Manufacturing Strategy by the White House Office of Science and Technology Policy, focused on opportunities in advanced manufacturing
- Department of Labor's chairing of a Task Force on Apprenticeship Expansion to identify strategies and proposals to promote apprenticeships, particularly in industries where they are insufficient
- DoD's program for Microelectronics Innovation for National Security and Economic Competitiveness to increase domestic capabilities and enhance technology adoption
- DoD cross-functional team for maintaining technology advantage Implementation of a risk-based methodology for oversight of contractors in the National Industrial Security Program, founded on risk management framework principles to assess and counter threats to critical technologies and priority assets.

Source: Assessing and Strengthening the Manufacturing and Defense Industrial Base and Supply Chain Resiliency of the United States, Sep 2018
Ten Risk Archetypes Threatening America's Manufacturing and Defense Industrial Base
| Sole source | Only one supplier is able to provide the required capability |
| Single source | Only one supplier is qualified to provide the required capability |
| Fragile supplier | A specific supplier is financially challenged / distressed |
| Fragile market | Structurally poor industry economics; potentially approaching domestic extinction |
| Capacity constrained supply market | Capacity is unavailable in required quantities or time due to competing market demands |
| Foreign dependency | Domestic industry does not produce the product, or does not produce it in sufficient quantities |
| Diminishing manufacturing sources & material shortages (DMSMS) | Product or material obsolescence resulting from decline in relevant suppliers |
| Gap in U.S.-based human capital | Industry is unable to hire or retain U.S. workers with the necessary skill sets |
| Erosion of U.S.-based infrastructure | Loss of specialized capital equipment needed to integrate, manufacture, or maintain capability |
| Product security | Lack of cyber and physical protection results in eroding integrity, confidence, and competitive advantage |
Source: Assessing and Strengthening the Manufacturing and Defense Industrial Base and Supply Chain Resiliency of the U.S., EO 13806 Report, Sep 2018
Industrial Base Fund
- to support the monitoring and assessment of the industrial base required by this chapter;
- to address critical issues in the industrial base relating to urgent operational needs;
- to support efforts to expand the industrial base; and
- to address supply chain vulnerabilities.
Authority
The authority of the Secretary of Defense to use the Fund under this section in any fiscal year is subject to the availability of appropriations for that purpose.
- Direct obligations from the Fund.
- Transfers of monies from the Fund to relevant appropriations of the Department of Defense.
Source: 10 USC 4817
Recent NDAA Language on the Defense Industrial Base
FY26 NDAA
Sec. 864. United States-Israel Defense Industrial Base Working Group
USD(A&S) in consultation with the Secretary of State, shall convene a working group to study the potential for greater integration of the defense industrial bases of the U.S. and Israel and the feasibility and advisability of including Israel in the National Technology and Industrial Base per 10 USC 4801.
Our Take: The Israeli industrial base has many promising companies that could contribute military solutions to the DoW directly or in partnership with U.S. companies. Including Israel in the NTIB would be a valuable step to reduce the barriers for collaboration and sales.
Sec. 1021. Pilot Program on Use of Automated Shipbuilding Technologies and Capabilities.
Not later than 90 days after the date of the enactment of this Act, the Secretary of the Navy shall establish a pilot program on the use of automated assembly technologies and capabilities in naval shipbuilding to reduce overall construction times and alleviate workforce constraints.
Our Take: Some of this is already underway but need to keep the focus on using the latest tech to bring our shipyards into the 21st century.
Sec. 1844. Collaborative Forum to Address Challenges to and Limitations of the Defense Industrial Base.
Requires SECDEF to identify one or more consortia or other entity to serve as a collaborative forum for government, private sector, academia, and nonprofit entities with expertise in advanced manufacturing to address the challenges to and limitations of the defense industrial base. Establish working groups focused on eliminating barriers, assessing supply chain fragility, and expanding domestic manufacturing and industrial capacity.
Our Take: Collaboration is always positive, this forum would have potential if used and led correctly. Need strong follow-through on actions identified.
Sec. 1845. Facility Clearance Acceleration for Members of Defense Industrial Consortiums.
Requires SECDEF to ensure each entity that is a member of the groups in Sec. 1844 is sponsored for a facility clearance, is provided access to sensitive compartmented information facilities and classified networks and invited to in-person meetings with relevant DoD personnel to discuss classified work.
Our Take: Industry writ large needs access to sensitive data to be effective. The security risk is much lower than the current risk of billions being invested in the wrong tech that doesn't move the needle.
Sec. 1846. Improvements Relating to Advanced Manufacturing.
USD(A&S) and USD(R&E) shall co-chair the Joint Defense Manufacturing Technology Panel, the Joint Additive Manufacturing Working Group, and the Consortium on Additive Manufacturing for Defense Capability Development. The USDs shall review the policies and procedures for qualifying, accepting, and managing supply chain products using advanced manufacturing.
Our Take: A positive step to improve use of advanced manufacturing tools and approaches.
Sec. 1847. Report on Surge Capacity in the Defense Industrial Base.
ASD(Industrial Base Policy) and Director DPCAP shall jointly submit to Congress a report on effects to identify and address regulations or policies that discourage or prevent contractors in the defense industrial base from maintaining or investing in surge capacity. Identify policies to incentivize industry to reduce or eliminate surge capacity, regulatory barriers discouraging or preventing contractors from maintaining or investing in surge capacity.
Our Take: As regular readers of this Substack know well, the U.S. DIB is not at all prepared for a wartime surge and would take years to ramp up if we were in a major war with a peer competitor. This report should be quickly acted upon to address the barriers and incentivize accelerated and novel approaches to scale surge capacity.
FY25 NDAA
Sec. 841. Enhancing Requirements For Information Relating To Supply Chain Risk.
Reduces the level of determination needed to exclude a source from a procurement based on perceived supply chain risk from USD(A&S) and DoD CIO to “procurement or other relevant officials of the covered agency.” It also reduces the information requirement to primarily a summary of the risk assessment.
Our Take: We think this is important discretion for lower level acquisition professionals who have evidence that certain supply chains have been compromised. The highly elevated level that this provision had before limited the ability of acquisition professionals to exercise the authority granted.
Sec. 874. Establish a Pilot Program for Access to Shared Classified Commercial Infrastructure
DoD establish a pilot program on streamlining access for small business and institutions of higher learning to share classified commercial infrastructure. Expand access to SCIFs and SAP facilities to securely perform work under existing classified contracts. Reduce the cost and administrative requirements. Increase opportunities for small businesses to have access to compete for classified contracts, and share infrastructure and prototyping proposed solutions.
Our Take: This is desperately needed for many small businesses that cannot fully understand the operational basis for a requirement or the employment details that are important for a company when developing a proposal. It is unclear if this will result in additional resourcing for “Rent a SCIF” type services or if it will meaningfully change the timelines for DCSA to certify a SCIF (which is currently on the order of years due to the backlog).
Sec. 876. Small Business Bill of Rights
Require SECDEF through the Small Business Integration Working Group, to develop and adopt a Small Business Bill of Rights for the DoD to ensure small business customer service issues and conflicts are resolved expeditiously.
Sec. 849. Supply Chain Illumination Incentives
Requires DoD to develop and implement incentives to encourage DoD contractors to implement and use policies, procedures, and tools to allow assessment and monitoring of supply chains for vulnerabilities, security, and noncompliance risks.

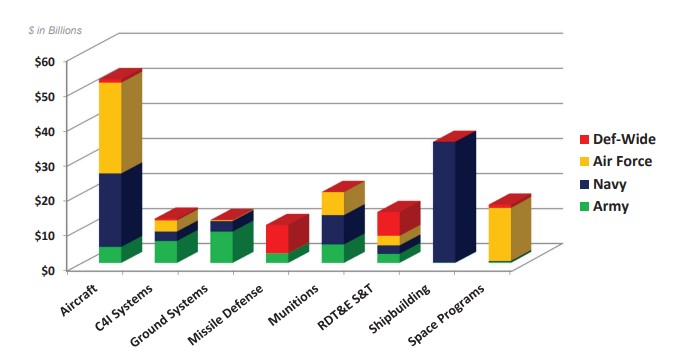
Defense Industry
Defense Industry Videos
32 videos
Additional Reading on Defense Industry
Defense Industry Research
The Slow Destruction of the Defense Industrial Base, Moshe Schwartz, Michelle Johnson, May 2022
Analyzing the Composition of the Department of Defense Small Business Industrial Base, Amanda Bresler, Alex Bresler, May 2022
Why Marketing Matters: Strengthening the Defense Supplier Base Through Better Communication with Industry, Amanda Bresler, Alex Bresler, May 2021
Industry Trade Associations

National Defense Industrial Association (NDIA)

Aerospace Industries Association (AIA)

Professional Services Council (PSC)

Silicon Valley Defense Group

National Security Space Association (NSSA)

AUSVI
